Independent Mortgage Advisor UK: How to Choose the Right Mortgage Adviser
Finding the right mortgage can be challenging when there are so many lenders, interest rates and mortgage products to compare. Whether you are buying your first home, moving to a new property or looking to remortgage, understanding your options is an important step towards making a confident financial decision.
An independent mortgage advisor can help you navigate the mortgage market, understand lender requirements and identify mortgage products that may suit your financial circumstances.
But what does an independent mortgage broker do, how much does mortgage advice cost, and how do you choose the right adviser?
In this guide, Ease Mortgages explains everything you need to know about finding an independent mortgage broker in the UK.
What Is an Independent Mortgage advisor?
An independent mortgage broker is a mortgage professional who provides advice on suitable mortgage products based on a customer’s financial circumstances and requirements.
Depending on the scope of their service, an independent adviser may assess products across the mortgage market rather than being restricted to a particular lender or a limited panel.
This can help borrowers compare different options without having to approach every lender individually.
A mortgage advisor may consider several factors when assessing your situation, including:
Your annual income and employment status.
Your deposit and savings.
Your credit history.
Existing loans and financial commitments.
Your property purchase or remortgage plans.
The monthly repayments you can comfortably afford.
Your preferences regarding mortgage terms and interest rates.
The aim is to help you understand the available options and choose a mortgage that is appropriate for your circumstances.
Importantly, the term “independent” should reflect the actual advice service being provided. Ask the adviser about their lender coverage and whether any restrictions apply.
Independent Mortgage advisor vs Bank: What Is the Difference?
When looking for a mortgage in the UK, you can approach a bank directly or seek advice from a mortgage advisor.
Both routes can be useful, but there are differences worth understanding.
Applying directly through a bank
When you approach a bank directly, you generally explore the mortgage products that the bank offers.
This may work well if you have already identified a suitable product and understand its eligibility requirements. However, you would need to compare other lenders separately if you want to explore the wider market.
Using an independent mortgage advisor
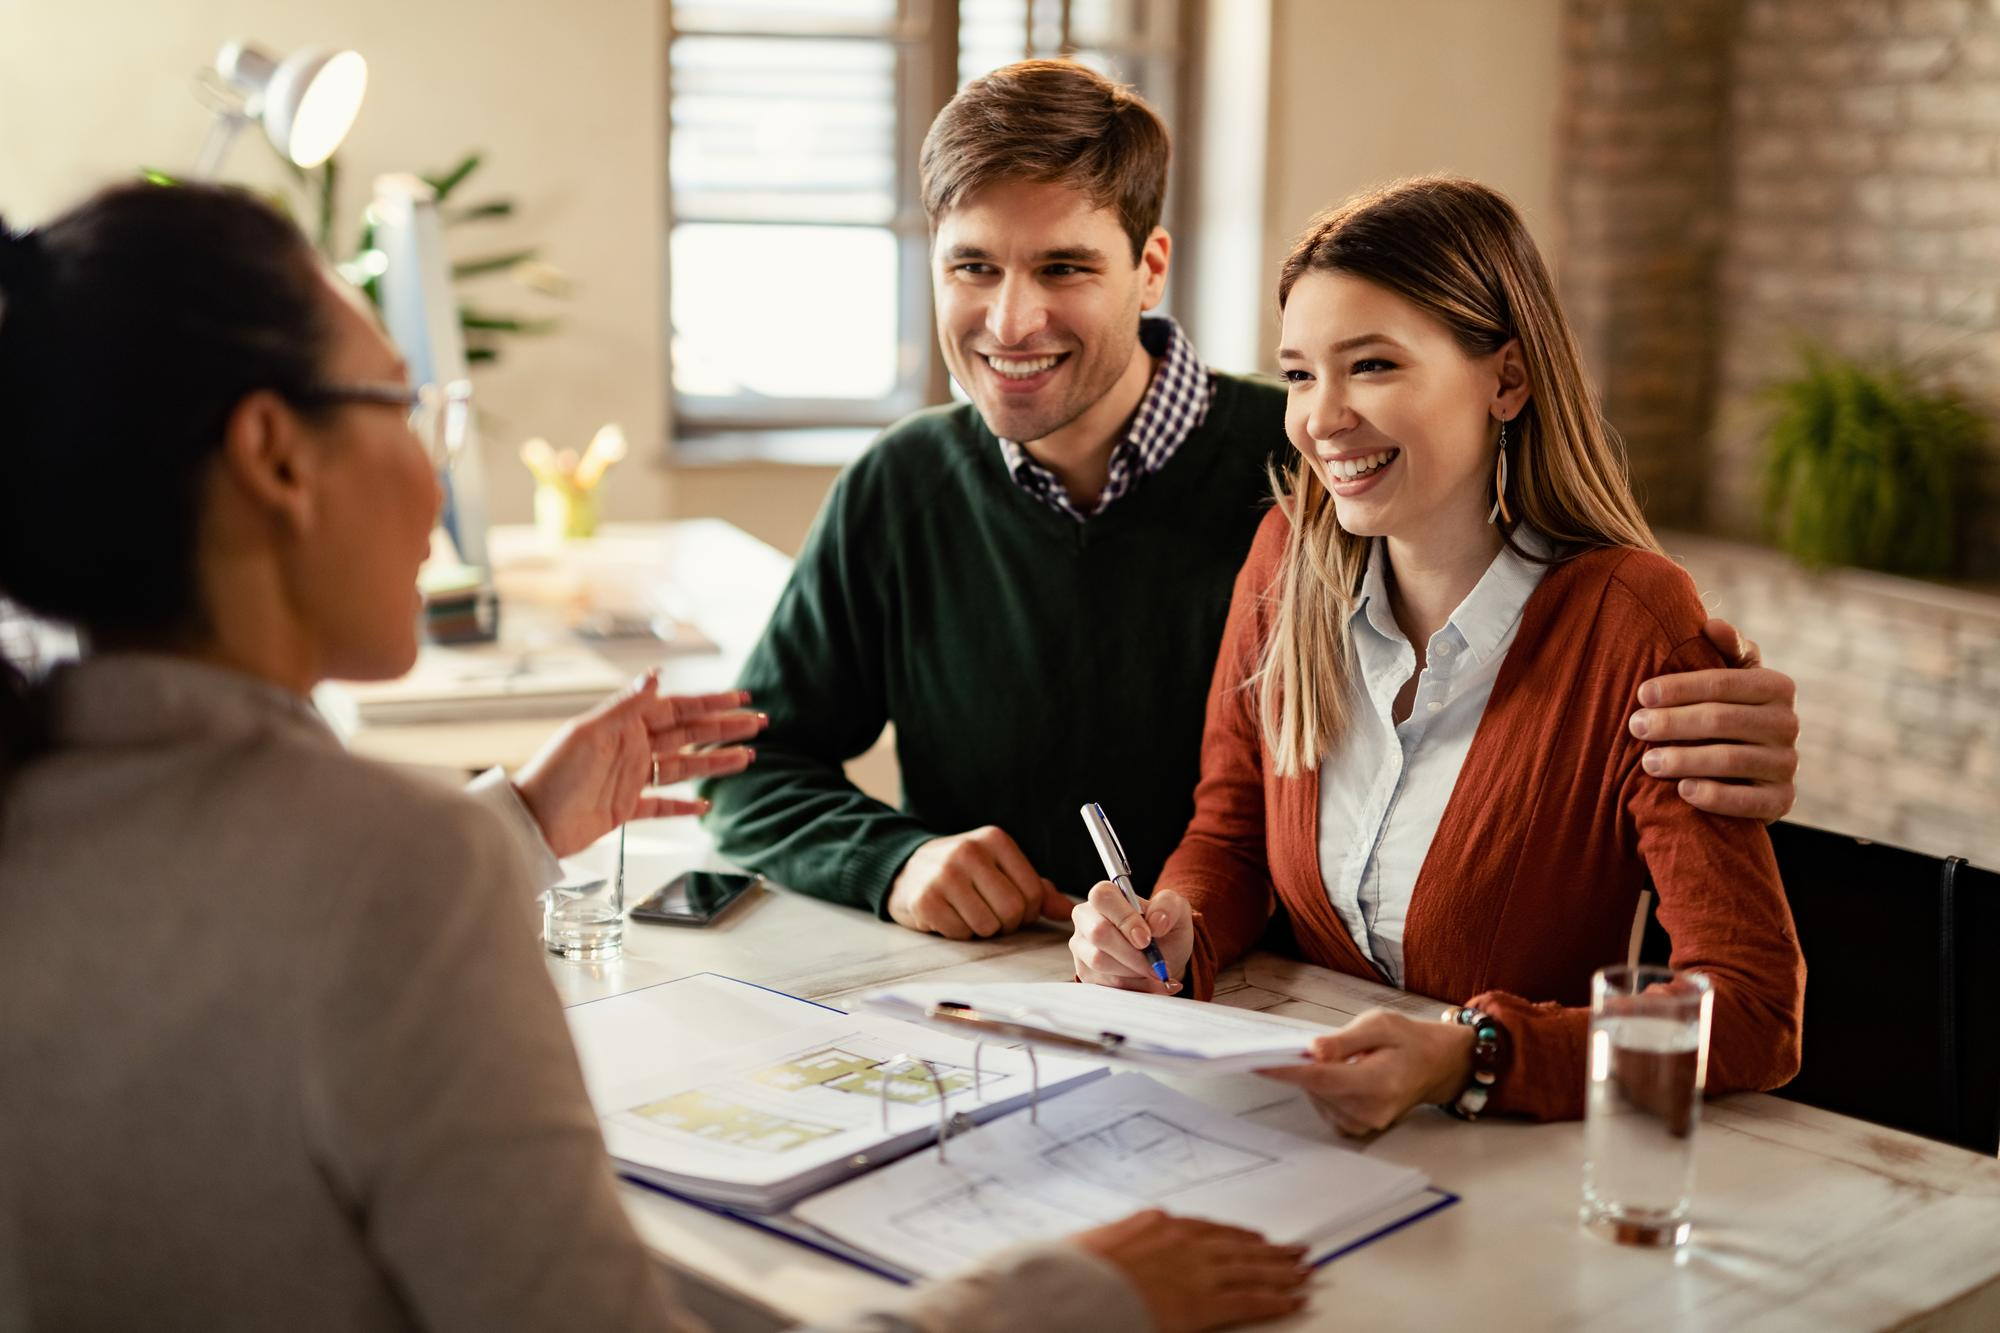
An independent mortgage advisor can assess your circumstances and recommend suitable options within the scope of their advice service.
Depending on their market coverage, they may compare products from multiple lenders and explain differences in interest rates, fees, eligibility criteria and mortgage features.
A broker may also help you prepare your application and communicate with the lender throughout the process.
Which option should you choose?
The right choice depends on your circumstances and how much support you need.
If you want to compare options across lenders or are unsure which products may suit you, professional mortgage advice can be helpful. If you prefer to use a particular bank’s products, applying directly may also be an option.
Before making a decision, compare the overall cost of the mortgage, not just the advertised interest rate.
What Are the Benefits of Using an Independent Mortgage advisor in the UK?
Working with an independent mortgage advisor can offer several potential benefits.
1. Access to a wider range of mortgage products
An adviser with broad market coverage may compare products from multiple lenders, helping you understand the differences between available options.
However, the number of lenders and products accessible depends on the adviser’s service and market coverage. Always confirm whether the adviser offers whole-of-market advice.
2. Advice based on your financial circumstances
Mortgage eligibility varies from one person to another. Your income, deposit, credit history and existing financial commitments can influence which products are suitable.
A mortgage adviser can assess these factors and explain which options may be worth considering.
3. Help understanding mortgage fees and interest rates
Mortgage products can include arrangement fees, valuation costs, early repayment charges and other conditions.
An adviser can explain these costs and help you compare the overall value of different mortgage products.
4. Support throughout the application process
Applying for a mortgage involves paperwork, affordability checks and lender assessments.
Depending on the service provided, a broker may help you organise documents, submit the application and respond to requests for additional information.
5. Guidance for different borrowing situations
Some borrowers have circumstances that require additional consideration, such as self-employment, variable income, a limited UK credit history or specific residency requirements.
An adviser may help identify lenders whose criteria are worth exploring, although approval will always depend on the lender’s assessment.
How Much Does an Independent Mortgage advisor Cost in the UK?
Mortgage broker fees vary depending on the adviser, the service provided and the complexity of your application.
Some advisor charge a fee for their advice, while others may receive commission from the lender. Some services may involve a combination of fees and commission.
Before proceeding, ask the broker to explain:
Whether an advice fee applies.
When the fee becomes payable.
Whether the fee is refundable if your application does not proceed.
Whether the broker receives commission from the lender.
What services are included in the fee.
You should also compare the mortgage product’s arrangement fees and other charges, as these are separate from the broker’s own fees.
The cheapest advice service is not necessarily the most suitable one. Consider the quality and scope of the service, lender access, transparency and how well the adviser understands your requirements.
What Should You Check Before Choosing a Mortgage advisor?
Choosing a mortgage adviser is an important decision because a mortgage can be one of your largest financial commitments.
Here are some useful checks to make before choosing a broker.
Check FCA authorisation
Verify the adviser or firm through the Financial Conduct Authority’s official register. Check that the firm is authorised for the relevant mortgage activities and that the service offered matches your needs.
You can use the FCA website at https://register.fca.org.uk/.
Ask about lender coverage
Find out whether the broker offers whole-of-market advice or works with a restricted panel of lenders.
This helps you understand how broad the comparison will be and whether any limitations apply.
Understand the fees
Ask for a clear explanation of the broker’s fees and any commission arrangements before proceeding.
Check the adviser’s experience
Ask whether the adviser has experience with circumstances similar to yours, such as first-time purchases, remortgages or applications involving variable income.
Read reviews carefully
Customer reviews can help you understand other people’s experiences with communication, service and the application process.
Look for consistent feedback rather than relying on a single review or a high rating alone.
Evaluate the communication process
Choose an adviser who explains the options clearly, answers your questions and keeps you informed about the next steps.
A good advice process should help you understand your choices rather than pressure you into a particular mortgage.
When Should You Contact an Independent Mortgage Broker?
It is often useful to explore mortgage advice before you make a property offer or commit to a particular borrowing arrangement.
You may want to speak with a mortgage broker if you are:
Buying your first home.
Moving to a different property.
Looking to remortgage an existing property.
Approaching the end of a fixed-rate mortgage deal.
Unsure how much you can afford to borrow.
Self-employed or receiving variable income.
Looking for mortgage options that fit specific residency circumstances.
An early conversation can help you understand your potential borrowing range and the documents you may need.
A mortgage in principle may also help you understand your approximate budget, but it is not a formal mortgage offer and does not guarantee approval.
How Does the Mortgage Application Process Work?
Although the details vary between lenders, the mortgage process generally follows several stages.
Step 1: Review your finances. Assess your income, expenditure, credit history, deposit and existing financial commitments.
Step 2: Discuss your requirements. Explain your property plans, preferred budget and any circumstances that could affect your mortgage options.
Step 3: Compare suitable mortgage products. Review relevant options, including interest rates, fees, repayment terms and eligibility criteria.
Step 4: Obtain a mortgage in principle. Where appropriate, obtain an initial indication of potential borrowing.
Step 5: Submit a full application. Provide the lender with the required financial and property information.
Step 6: Complete lender checks. The lender assesses affordability, verifies documents and arranges an appropriate property valuation.
Step 7: Receive a mortgage offer. If the lender approves the application and its conditions are met, it may issue a formal offer.
Step 8: Complete the purchase or remortgage. The relevant legal and completion procedures are carried out.
The time required depends on your circumstances, the lender, the property and the legal process. Preparing documents early and responding promptly to requests can help avoid unnecessary delays.
Common Mistakes to Avoid When Choosing a Mortgage Broker
Before selecting an adviser, avoid these common mistakes.
Choosing based only on the lowest interest rate: Fees, early repayment charges and other product conditions affect the overall cost.
Not checking lender coverage: Understand whether the broker offers whole-of-market advice or works with a restricted selection of lenders.
Ignoring broker fees: Request a clear breakdown of the cost of advice before agreeing to proceed.
Assuming mortgage approval is guaranteed: Neither a broker nor a mortgage in principle can guarantee that a lender will approve your application.
Providing incomplete financial information: Accurate information helps the adviser assess your circumstances and identify relevant options.
Failing to verify regulatory status: Check the relevant firm or adviser on the FCA register before relying on their mortgage advice.
Taking time to complete these checks can help you make a more informed decision.
Find Mortgage Advice With Ease Mortgages
Choosing a mortgage involves more than finding the lowest advertised rate. It requires an understanding of your financial circumstances, lender eligibility requirements, fees and the long-term cost of borrowing.
If you are looking for an independent mortgage broker in the UK, Ease Mortgages can help you understand the mortgage advice process and explore options relevant to your circumstances.
Whether you are purchasing your first home, moving property or considering a remortgage, getting the right guidance can help you approach the next steps with greater confidence.
Visit Ease Mortgages to learn more and make an enquiry about your mortgage requirements.
Mortgage eligibility and available products depend on your individual circumstances and lender criteria. Mortgage approval is not guaranteed. Check the adviser’s regulatory status, lender coverage and fees before proceeding.
Frequently Asked Questions
What is an independent mortgage broker in the UK?
An independent mortgage broker provides mortgage advice based on a customer’s circumstances and the scope of the adviser’s market coverage. Ask whether the service is whole-of-market or restricted to particular lenders.
Is an independent mortgage broker better than a bank?
Neither option is automatically better for everyone. A broker may help compare products across multiple lenders, depending on their coverage, while a bank can advise on its own mortgage products. Compare the available options, costs and suitability for your needs.
Do independent mortgage brokers charge fees?
Some charge advice fees, some receive lender commission, and some use a combination of both. Ask for a clear explanation of all charges and commission arrangements before proceeding.
Can a mortgage broker guarantee approval?
No. A broker can help assess your circumstances and identify potentially suitable options, but the lender makes the final decision after reviewing your application.
How do I check if a mortgage broker is authorised?
Use the Financial Conduct Authority’s official register to check the firm or adviser and confirm that the relevant mortgage activities are covered.
When should I speak to a mortgage broker?
You can seek advice before searching for a property, when preparing to make an offer, when reviewing your borrowing options or when considering a remortgage. Starting early can help you understand your budget and the documents you may need.
Can an independent mortgage broker help with remortgaging?
Yes, depending on the adviser’s services. A broker may help compare suitable remortgage options, fees and product terms based on your circumstances.
Author: Ease Mortgages
Suggested reviewer: A suitably qualified mortgage adviser at Ease Mortgages
Last reviewed: October 2026
How Much Can I Borrow for a Mortgage in the UK? A Complete Guide for 2026
Remortgage Services in UK: A Complete Guide for Homeowners
Independent Mortgage Advisor UK: How to Choose the Right Mortgage Adviser
How Can Indians Living in the UK Get a Mortgage in 2026?